
Insurance direct mail marketing timed to the X-date
94%
$2.1m
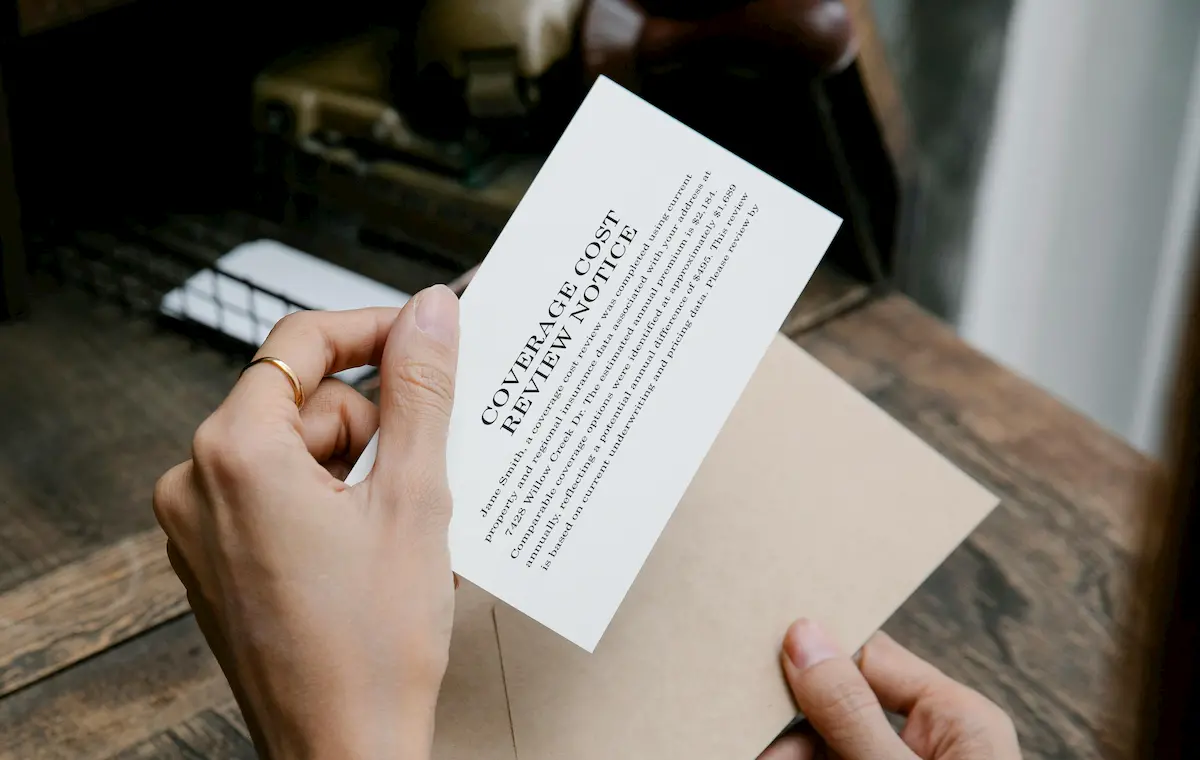
Why insurance mail fails when it ignores the renewal cycle
Most insurance mail lands at a random point in the policy year. The household already renewed, or the renewal is nine months out, and the piece goes in the bin. Our insurance direct mail marketing starts from the expiration date and the carrier the prospect holds today. We mail into the window when a quote can actually replace a policy, and we follow each response through your agency management system to the bound policy.
How an insurance direct mail program runs from list to bound policy
We build insurance direct mail marketing around x-dates, carrier appetite, and state rules, then trace each response to a bound policy. Ask for a quote.

List sourcing by carrier and x-date
Lists are pulled on current carrier, policy expiration month, property and vehicle data, and the products your appetite guide accepts. State DNC and suppression files run before any record is counted.

Creative that clears compliance before print
Each piece is written for one line and one state, with disclosures placed where a reviewer can find them. Medicare pieces follow CMS marketing rules. Nothing prints until compliance signs.
Print and drop schedule tied to renewal windows
Drops are staged so the piece arrives 30 to 45 days ahead of the expiration date. Print runs are split by mail week, not dumped in one batch.
Tracking numbers and CRM attribution
Every drop carries its own CallTrackingMetrics number and reference ID. The lead lands in Velocify, HubSpot, or Salesforce with campaign, segment, and creative attached, and the record is updated when the policy binds.
Insurance lines we mail for and how each one is targeted
We run programs for independent agencies, MGAs, and captive offices. Each product line gets its own list logic, creative, and tracking numbers, because an auto renewal and a Medicare enrollment period do not behave the same way.
What a mail-to-bound-policy program changes for your agency
You stop paying four vendors who each own a slice and none of the result. List, creative, print, tracking numbers, and CRM attribution sit in one system with one reporting line. When a drop underperforms, we can see whether the list, the timing, or the offer missed, and we fix that part. When you add a state or a product line, the same pipeline carries it. Price an insurance mail drop by calling (844) 936-3433.
What Carriers Say
Insurance companies measuring acquisition in policies, not impressions.
We finally know which mail pieces produce which policies. That visibility changed how we allocate.
Justin Case
Carrier CEO, Premium Heights, OH
Compliance used to slow everything. Now it is built in before we discuss creative.
Polly C. Holder
Agency Owner, Actuarial Falls, PA
Medicare campaigns took eight weeks to launch. Now we are live in two.
Deb Ductible
Medicare Lines Director, Claimsville, NJ
Replaced three vendors. Simpler. Faster. Actually know what works now.
Ann Derwriter
COO, Subrogation Springs, IN
Commercial lines up 34%. Business formation targeting made the difference.
Liam Bility
Commercial Lines VP, Riskville, CT
Frequently Asked Questions
The expiration date is the strongest signal we have. A household that renews in March cannot be moved in September. We pull lists by expiration month and mail 30 to 45 days ahead of it, so the quote request arrives while the policy can still be replaced.
Yes. Current carrier is a standard list attribute for auto and home. If your appetite guide favors displacing a specific carrier, or if a carrier has taken a rate action in your state, we build the list around that carrier and time the drop to it.
Auto, home, umbrella, term and whole life, final expense, Medicare Supplement and Advantage, and commercial lines including BOP, general liability, and workers comp. Each line gets its own list criteria, creative, and compliance review.
State DNC and internal suppression files run before the list is counted. Disclosures are written per state and per line. Medicare pieces follow CMS marketing rules. Response numbers are set up so consent is captured on the call and stored on the lead record.
Each drop carries its own tracking number and reference ID. The call or form creates a lead in your CRM with campaign, segment, and creative already attached. When the policy binds in your agency management system, that status writes back to the same lead ID.
A list count by state, line, and expiration month, a print and postage price per piece, creative and compliance review, tracking numbers, and CRM setup. Call (844) 936-3433 and we can scope it in one conversation.
Start with a system review
If you want campaigns, hire a vendor. If you want acquisition operated as a system with visibility into revenue, from the mailbox to the CRM to the funded loan, CoreLeadz is built for that.